Disclosure: This post may contain affiliate links. If you purchase through one of our links, we may earn a commission at no additional cost to you.
The Going Tiny Series, Part 4 of 45 · Guide 1 of 5: The Tiny House Money Plan
A free chapter goes up every day. See every part. Rather have it all at once, with printable worksheets? Get the Going Tiny Toolkit.
A smaller home is usually sold on the idea that it costs less to live in. Often that’s true. Sometimes it isn’t. The only way to know is to compare your real current monthly cost with your real expected cost on the new path.
Step 1: What does your home cost you now?
Add up everything you spend to keep a roof over your head. Not just rent or mortgage. On Worksheet 1 (Your Current Monthly Cost of Living) you’ll list:
- Rent or mortgage payment
- Property taxes and homeowner’s insurance (if not in your payment)
- HOA or condo fees
- Electric, gas, heating oil, propane, water, sewer, trash
- Internet and phone
- Repairs and upkeep (look back at last year and divide by 12)
- Yard care, snow removal, pest control
- Storage units
- Commuting costs tied to where you live
Many readers are surprised by the total. A paid-off house is not free: taxes, insurance, utilities, and repairs on an older, drafty house can easily run several hundred dollars a month or more.
Step 2: What would the smaller path cost each month?
Do the same list for your chosen path. Include anything new: lot rent, a loan payment, RV insurance, propane, internet, a storage unit you plan to keep, and a maintenance reserve. A simple rule many people use is to set aside about 1 percent of the home’s value per year for repairs, divided into monthly amounts.
Want to do this on paper?
The printable PDF of The Tiny House Money Plan has fill-in worksheets for this step, including:
- Your Current Monthly Cost of Living
- Path Cost Estimator
They come with all five guides in the Going Tiny Toolkit.
Step 3: Compare, then decide what the difference is worth
Worked example 1: Linda, renter on a fixed income
Linda is 66, lives alone, and gets Social Security plus a small pension. She rents a two-bedroom apartment she no longer needs.
| Monthly cost | Now: 2-bedroom apartment | Smaller: used park model in a community |
|---|---|---|
| Rent or lot rent | $1,450 | $650 (includes water, sewer, trash) |
| Electric and gas | $165 | $95 |
| Water, sewer, trash | $45 | $0 (in lot rent) |
| Internet and phone | $90 | $90 |
| Renter’s or home insurance | $18 | $55 |
| Taxes or registration | $0 | $20 |
| Maintenance reserve | $0 | $35 |
| Storage unit | $0 | $0 (she decluttered) |
| Total | $1,768 | $945 |
Linda would spend about $823 less per month. But she needs about $42,000 up front: roughly $38,000 for a good used park model and $4,000 for moving and setup. If she has $15,000 saved, she’s $27,000 short. Should she borrow, wait, or choose a cheaper unit? That’s the conversation the rest of this guide helps you have. One option: a chattel loan on the park model (if a lender will approve one for her situation) could cost less per month than the savings, leaving her ahead. Another: keep renting while saving $500 a month, which gets her there in about four and a half years. A third: look for a less expensive used unit.
Worked example 2: Dan and Ruth, homeowners
Dan and Ruth own a four-bedroom house with a $700 mortgage payment and $9,000 a year in taxes and insurance. Their utilities run $320 a month and repairs averaged $3,600 last year.
| Monthly cost | Now: 4-bedroom house | Smaller: 600 sq ft cottage, paid in cash |
|---|---|---|
| Mortgage | $700 | $0 |
| Taxes and insurance | $750 | $260 |
| Utilities | $320 | $140 |
| Repairs and upkeep | $300 | $120 |
| Yard care | $80 | $20 |
| Total | $2,150 | $540 |
Over $1,600 a month freed up. But the cottage only works if their house sale actually covers it after all selling costs (Part 6) and if they can find a lot where a small home is allowed.
When smaller doesn’t save money
If you’d trade a $900 rent for a $650 lot rent plus a $700 loan payment, your housing cost goes up, at least until the loan is paid off. That can still be a reasonable choice if you’d own the home at the end, but go in with your eyes open. Run both numbers on Worksheet 1 and Worksheet 2.
A real home from Tiny House Talk

Photo: Exploring Alternatives and Living in Tiny G
Her monthly costs dropped to about one-third
Doing this comparison changed Anne-Marijke's retirement. She realized regular housing costs would have kept her working until about 80. She bought a tiny house shell, finished the inside with her daughter for about $60,000 USD, and parked in a backyard for about $200 a month. Her living costs fell to about one-third.
The “years to break even” check
If a smaller path costs money up front but saves money each month, you can estimate how long it takes to come out ahead:
Up-front cost ÷ monthly savings = months to break even
For Linda: $42,000 ÷ $823 is about 51 months, a little over four years. After that, the savings are hers to keep. If a path takes 20 years to break even, and you’re 70, it may not be the best fit. If it takes three years, it probably is.
A real home from Tiny House Talk
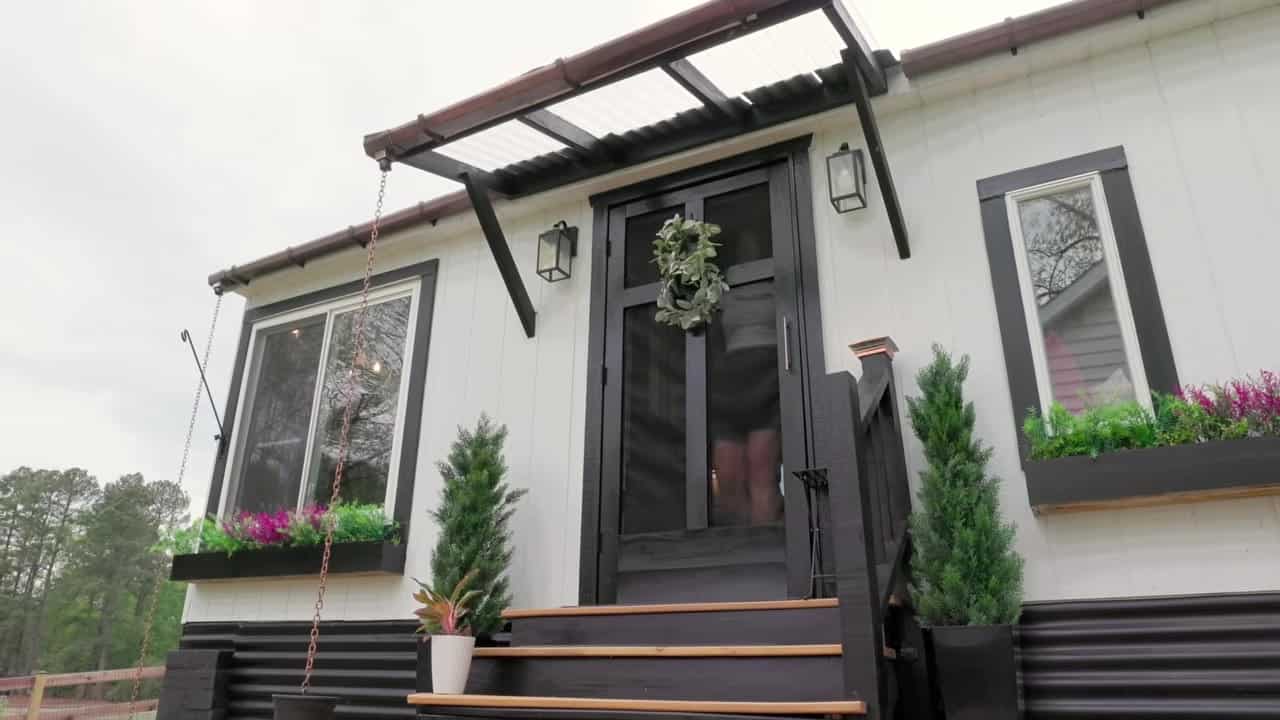
Photo via Tiny Home Tours/YouTube
A shed-shell tiny house that paid for itself in two years
Here is the break-even check in real life. Margo started with an $8,800 Amish shed shell in Central Virginia and finished it for about $47,000 all in, including about $10,000 of hired plumbing. Compared with rent and utilities in Richmond, she figures she earned the cost back in about two years.
Your turn
What's the money question you're stuck on right now? Tell me in the comments.
Want the whole series in one place?
This series is free to read here, and it always will be. If you’d rather have it as five clean, printable PDFs, that’s the Going Tiny Toolkit:
- The Tiny House Money Plan (the guide this chapter comes from): real 2026 cost ranges, a savings plan for any income, and every way people pay
- Where Can I Put It?
- Tiny Without the Ladder
- Bringing Them On Board
- Your First Tiny Steps
Every guide adds printable worksheets and a 30-day action plan, and Tiny Without the Ladder comes with the bonus One-Level Floor Plan Idea Book (18 to-scale floor plans). All five are $47, with a 30-day refund.
← Previous: Part 3: The Cheapest Legal Way to Live Smaller, Based on Your Situation
Next (tomorrow): Part 5: How to Save for a Tiny or Small Home on Any Income
Not sure which part matters most for you? The free 10-minute What’s Really Holding You Back? quiz tells you where to start. And to get a new part (and a new home) in your inbox each day, join the free Tiny House Newsletter.
Disclosure: This post may contain affiliate links. If you purchase through one of our links, we may earn a commission at no additional cost to you.


Alex
Latest posts by Alex (see all)
- Your Monthly Number: What You Spend Now vs. Living Smaller - October 22, 2026
- Shipping Container Cabins on Fish Creek: A Tiny Hotel Near Saratoga, New York - October 21, 2026
- Belle Tout Keeper’s Loft: Sleep in the Tower of an 1832 Clifftop Lighthouse - October 21, 2026